The most important number in the economy has hit its highest level since 2007, and Wall Street can’t decide if this is good or bad. That number is the 10-year Treasury yield, the interest rate that the U.S. government pays to borrow money for a decade and on which almost every other loan in the
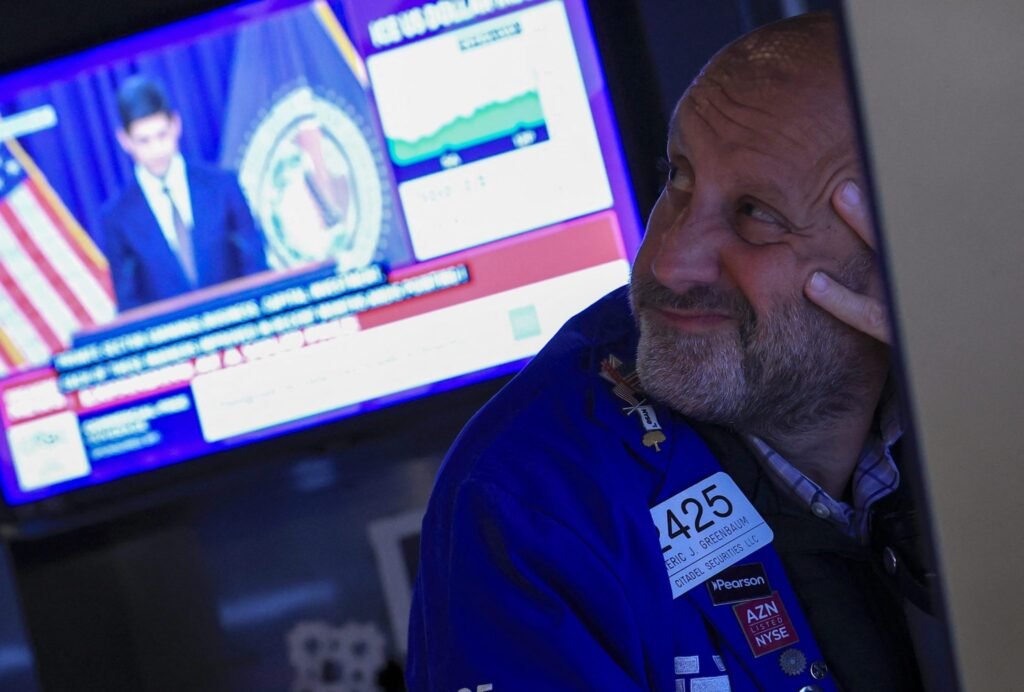
The most important number in the economy has hit its highest level since 2007, and Wall Street can’t decide if this is good or bad.
That number is the 10-year Treasury yield, the interest rate that the U.S. government pays to borrow money for a decade and on which almost every other loan in the country is predicated. It hit 5.21% on Friday, and the average 30-year mortgage rate jumped to 7.45% alongside it; car loans, credit cards, and business loans will follow.
This happened after the Federal Reserve raised rates last week, its first hike since 2023, to cool off the economy, with markets seeing roughly 70% odds of another hike in October.
Bonds kept selling off, and Wednesday’s auction of five-year Treasuries drew the weakest demand since 2018.
Whether that’s a problem, though, depends on why it’s happening. Yields can rise mostly for two reasons: because the economy is booming or because investors are losing their taste for U.S. debt. Economists are split on which explanation applies here.
What is a bond anyway?
It’s helpful to go back to the basics of bond dynamics. A bond is an IOU; when you buy a Treasury, you lend the government money, and it pays you interest on that loan. That rate of interest is the bond yield.
The yield moves with demand; when fewer investors want to lend, the government has to offer a higher rate to find buyers. And because lenders base the price of mortgages, auto loans, and the like on the government’s rate, everyone’s borrowing costs rise with it.
That affects stocks, too. If a risk-free government bond can pay you 5%, investors might demand a better reason to own riskier stocks, and might pay less.
Yields for 10- or 30-year bonds price in what investors expect the Federal Reserve to do over the long term. If you think the Fed will hold rates at around 4% for years, you won’t lend to the government for 10 years at anything less than that, because you might as well just buy short-term bonds and keep rolling them over.
Yields also price in the “term premium,” the extra pay that investors demand for tying up their money for that long. A lot can go wrong in a decade; there could be a war, inflation could spike, the deficit could balloon, another pandemic could sweep through the economy.
If yields are up because investors expect that the Fed will keep rates high, it’s usually because they expect that the economy will remain strong, with robust profits and investments such that the Fed won’t have to incentivize further growth through cutting. Strong economies mean strong profits, which is when stocks can handle rising yields.
But if yields are up because the term premium is rising, investors aren’t feeling strong about U.S. growth. Rather, they’re demanding more pay to hold U.S. debt, just in case of some risk.
So which is it now? Depends on whom you ask.
The case for boom
The optimists say yields are rising because the economy is strong and there’s real growth, much of it from AI. The largest hyperscalers are on track to devote nearly $800 billion to capital expenditures this year and more than $1.1 trillion in 2027, according to Goldman Sachs, the biggest tech investment cycle relative to GDP since the beginning of the railroad industry.
A booming economy pushes up prices, so the Fed raises rates to keep inflation in check, and investors expect it to keep them there for a while.
Matthew Klein, an economics commentator and author of The Overshoot newsletter, agrees that the Fed is starting to hike for the right reason: The economy has been running hot for years, and it’s finally getting around to being upbeat on growth and jobs.
Similarly, analysts at Jefferies say the market is “underestimating U.S. equities’ ability to absorb longer-term rates,” pointing to strong, broad earnings growth.
The case for bust
But pessimists worry about the term premium starting to climb amid risks that the Fed can’t control.
Start with the debt: Washington is making no effort to rein in the deficit, wrote Thierry Wizman of Macquarie Group, and the war with Iran, now approaching its eighth month, is making it bigger. Every single dollar of that deficit means more Treasuries for investors to absorb, testing the limits of demand in the bond market.
Plus, all that AI spending now exceeds the hyperscalers’ available source of cash, so they’re issuing bonds that compete with Treasuries for investors, in an economy where Americans don’t save that much.
Without a break in AI spending or the Iran war, Wizman wrote, yields “will stay lofty.”
For more tech updates, stay tuned to our blog.