France’s worsening unrest is exposing how difficult it could be for the government to rein in spending and restore confidence in its battered bond market. Mass protests over rising living costs and poor school conditions swept across France over the weekend, with violence and looting breaking out in several cities. Shops were ransacked in Paris
France’s worsening unrest is exposing how difficult it could be for the government to rein in spending and restore confidence in its battered bond market.
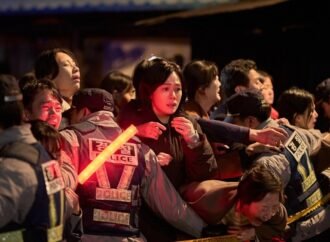
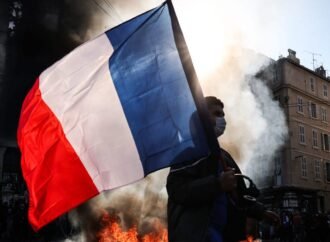
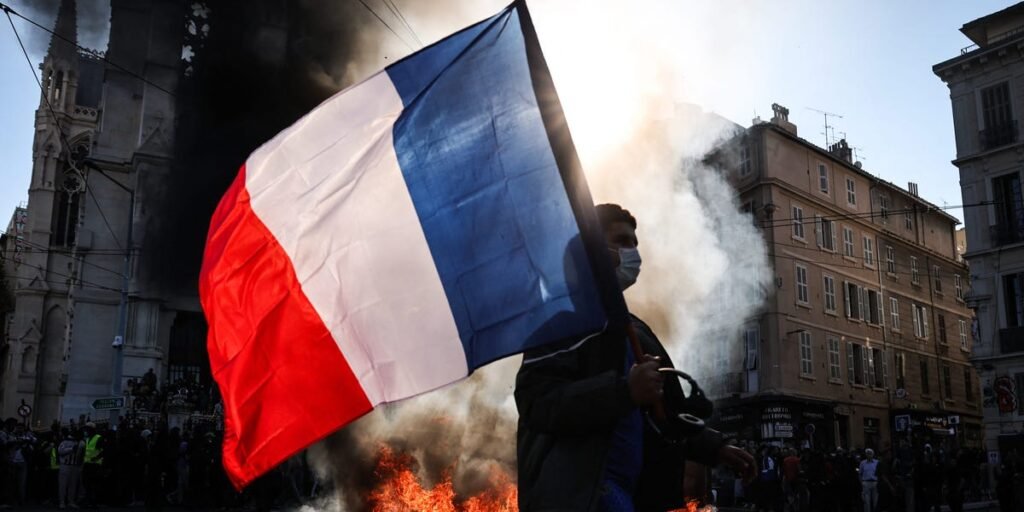
Mass protests over rising living costs and poor school conditions swept across France over the weekend, with violence and looting breaking out in several cities. Shops were ransacked in Paris and other cities, while a fire devastated the historic town hall in Limoges, west-central France.
The unrest adds to the challenges facing a government already struggling to pass a budget and bring its debt under control ahead of next year’s presidential election.
French government bonds, known as OATs, have been among the hardest hit in a global bond selloff fueled by inflation fears, higher interest-rate expectations, and concerns about government debt.
“French OATs continue to be the punching bag in the ongoing selloff in sovereign bond markets,” Elias Hilmer, a markets economist at Capital Economics, wrote in a note on Friday.
French bond yields have risen much faster this year than those on German government debt — considered among Europe’s safest — widening the gap between the two as investors demand a bigger premium to hold French bonds.
Early on Monday, France’s 10-year OAT yield was 8 basis points higher at 4.86%, while Germany’s 10-year bond yield was flat at 3.41%.
Why France’s debt problem is so hard to fix
Investment manager Ninety One warned Monday that if France fails to pass its 2027 budget, its deficit could exceed 6% of GDP next year — more than double the European Union’s 3% limit.
Even passing the budget would offer only a temporary fix, said Sahil Mahtani, director at Ninety One’s Investment Institute. France’s presidential election next year could be followed by another parliamentary election, potentially leaving the country without a clear governing majority and extending budget uncertainty into 2028.
The fiscal dilemma is particularly acute over pensions, where reforms could help stabilize France’s debt trajectory but face strong political opposition.
“If we want to see some real improvement in the debt dynamic of France, it will need to reform the pension system, which costs much more money than elsewhere. The issue for that is that it’s highly unpopular,” Charlotte de Montpellier, ING’s senior economist covering France, said in a webinar on Thursday.
Those political and fiscal challenges could leave French bonds increasingly out of step with the rest of Europe’s debt market, Capital Economics’ Hilmer wrote.
While falling energy prices could ease pressure on European interest rates and provide relief to bonds across the region, concerns about France’s finances and political instability could keep its borrowing costs elevated.
European Central Bank could be reluctant to intervene if French bond yields rise because of genuine concerns about the country’s finances rather than broader market dysfunction, Hilmer warned.
“Given the perilous state of France’s public finances and the uncertainty around the elections, we think French spreads may widen further over the coming year,” he wrote.
He forecast that the gap between French and German bond yields could widen from around 140 basis points to 200 basis points by the end of 2027, even as similar gaps narrow for most other eurozone countries.
Keep following us for the latest insights.