We may have already reached “peak AI.” Michael Feroli, the chief economist at JPMorgan, said on Thursday that history will likely record 2026 as the year that the AI spending boom reached its zenith, but that doesn’t mean investors should the the economy and markets will suffer. “Peak AI, at least in its impact on
We may have already reached “peak AI.”
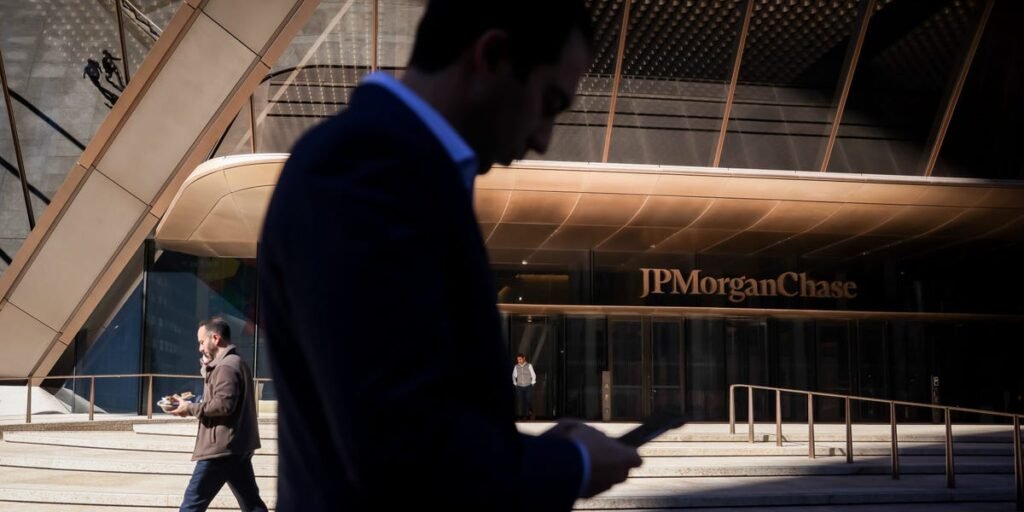
Michael Feroli, the chief economist at JPMorgan, said on Thursday that history will likely record 2026 as the year that the AI spending boom reached its zenith, but that doesn’t mean investors should the the economy and markets will suffer.
“Peak AI, at least in its impact on aggregate demand, will likely be 2026,” he wrote in the bank’s 2027 economic outlook. “Even before the elections, spending growth on the AI buildout was set to slow slightly next year.”
Feroli isn’t the only economics pro to suggest that the AI peak may have already arrived. In August, New York University finance professor Aswath Damodaran said that it had likely taken place several months prior, predicting that AI stocks were destined for more pain.
Anxiety around the health of the AI trade and questions regarding when high spending will pay off have sparked bouts of intense volatility this year. Big swings in the tech sector were exacerbated most recently by the scandal surrounding Nvidia CEO Jensen Huang and his subsequent resignation.
In Feroli’s view, though, while the AI boom may have already peaked, capex spending isn’t likely to decline by very much, and, more importantly, it won’t have a severe impact on the wider economy when it doesn.
“We expect any easing in AI-related spending to be moderate and partly offset by other supports. Consumers are soon to benefit from falling retail gas prices, as energy markets are finding ways around the stall in Mideast peace talks.”
The economist noted that the labor market has remained relatively strong throughout the AI boom. He added, though, that while there’s little evidence that AI is responsible for widespread layoffs, the perception that it’s a job killer may be working against workers in salary negotiations, helping companies pocket more profits as a result.
For some investors, this type of economic interdependence may be worrisome, as it underscores how much of the US economy has come to rely on ongoing AI growth. Economists such as Mark Zandi have raised concerns regarding what may happen if it starts to slow.
“The dominant feature of the US economy is AI: the massive buildout, the asset market spillovers, and the hotly debated productivity and labor market effects,” Feroli noted. “When the economy flies on one engine, concerns about the functioning of that engine are magnified.”
Torsten Sløk, chief economist at Apollo Global, made a similar case in a blog post on Thursday, stating that the AI boom has dwarfed all other economic engines and has been responsible for 65% of GDP growth so far this year.
“AI is the number one source of growth for the US economy, and anyone making statements about the 2027 outlook for equity and credit markets is implicitly making assumptions about the pace and magnitude of the AI data center buildout,” Sløk wrote.
For Feroli, though, the underlying message for investors is that while AI spending may start to decline in 2027, the impact will likely be offset by growth in other areas.
Keep following us for the latest insights.